Newsletters




Gulp.
We need to talk about Japanese government bonds.
No. Please come back. There will be no equations. Nobody will be asked to explain duration risk. You may keep your shoes on.
I used to cover global markets for a living, which is how I acquired the deeply antisocial habit of noticing Japanese bond yields.
I thought I had beaten it.
But Japanese government bonds are a little like the terms and conditions of the global economy. Nobody reads them. Everybody clicks “Agree.” I am one of the unfortunate people who used to get paid to read them.
And occasionally, several thousand miles away, something expensive happens.
Something expensive may be happening to Türkiye.
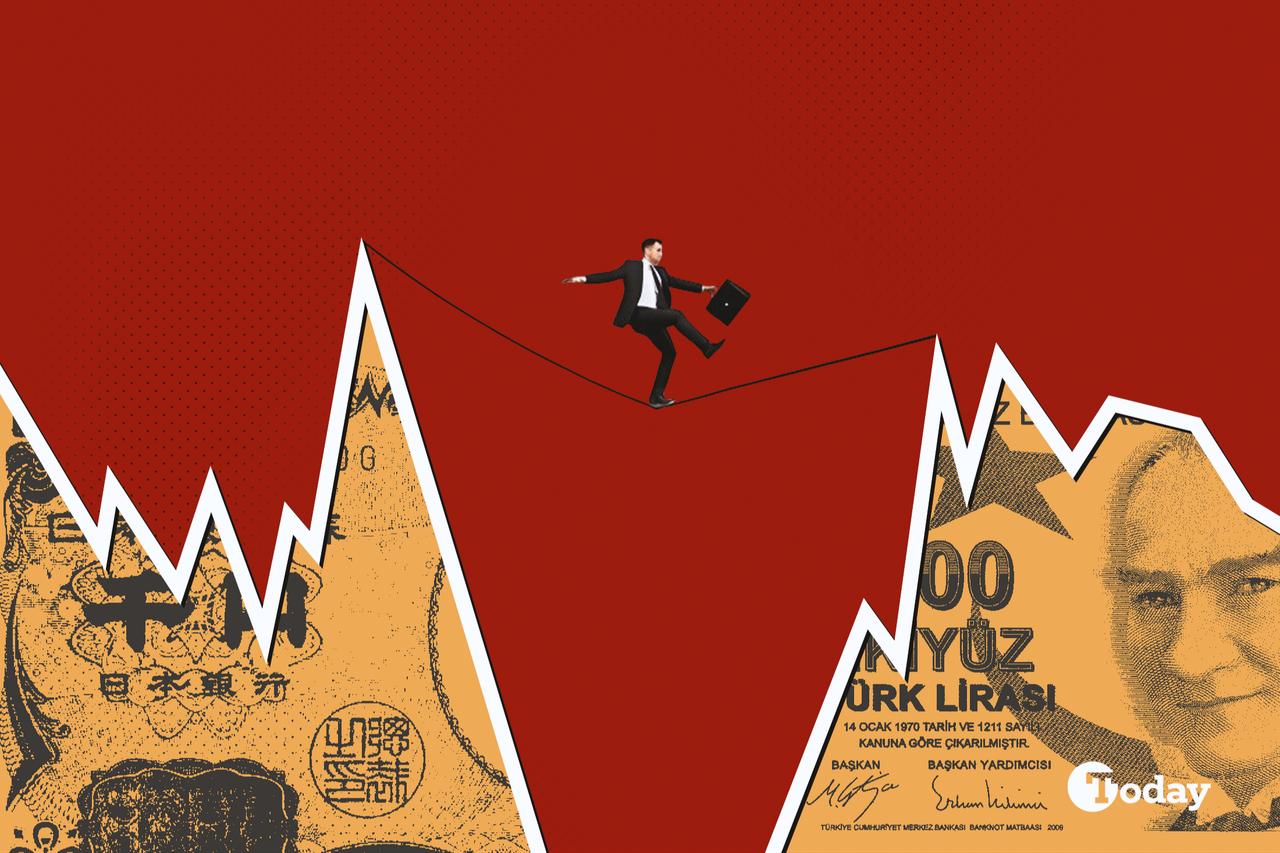
For roughly three decades, Japan was the world’s financial bargain basement. Interest rates hovered around zero. Traders could borrow yen for almost nothing and put the money somewhere paying considerably more.
This became known as the carry trade: Borrow cheap money. Buy something, paying more. Pocket the difference. Try not to get killed.
Few places have recently dangled a juicier piece of meat before these people than Türkiye.
Türkiye’s central bank interest rate is 37%. Lira deposits have recently paid around 44%. Mortgages cost roughly 42% and general-purpose consumer loans an eye-watering 63%.
Imagine borrowing yen cheaply in Tokyo, swapping them for lira and buying a Turkish investment paying a gigantic interest rate.
As long as the lira behaves, you pocket the difference. The Turkish version is understandable: borrow cheaply over there, earn extravagantly over here, and pray nothing horrible happens before you get your money home.
For a while, this worked. Foreign money returned. Türkiye rebuilt reserves. After years of economic experiments, international investors were presented with something they desperately crave: the possibility of being bored again.
Then Japan stopped cooperating.
Sorry, time to eat your peas.
Japanese 10-year government bonds now pay above 3%, while the Bank of Japan has pushed its main interest rate to 1.25%, a 31-year high. Stay with me. Two more bites and you can have dessert.
Now borrowing yen costs more. If the yen rises, repaying borrowed yen costs more too. Either can chew through the profit in Türkiye.
So traders sell the Turkish investment, sell the lira, buy yen and go home.
That is really all you need to know: The more attractive Japan becomes, the less irresistible Türkiye looks.
And not just to people borrowing yen. Japanese investors who can suddenly earn decent money at home have less reason to send it abroad.
Other investors may decide Türkiye’s spectacular rates aren’t quite spectacular enough for the adventure involved.
Markets recently offered a small preview. As traders prepared for tighter Japanese policy, the yen jumped almost 5% against currencies popular with carry traders, including the Turkish lira.
No Turkish crisis followed. But somewhere in the terms and conditions, the price had changed.
Now our tedious little bond story enters the Turkish kitchen.
Türkiye buys enormous quantities of energy, machinery and other necessities from abroad. A weaker lira makes them cost more.
That is particularly awkward when consumer prices are already 31.5% higher than a year ago. Food is up 33.8%, transportation 35.1%, and housing and utilities nearly 40%.
The central bank therefore has little room for another nasty surprise from the currency—and less freedom to bring interest rates down.
Now put away the bond charts and follow the money.
A fund manager in Tokyo decides a Japanese bond paying 3% suddenly looks respectable and sells some Turkish investments. More lira hit the market and the currency slips.
A Turkish importer still needs to buy natural gas, machine parts, fertilizer or cooking oil in dollars or euros. Now he needs more lira to buy the same amount.
He raises his price. The wholesaler raises hers. The shopkeeper looks at the new invoice, sighs, reaches for the pricing gun and starts clicking.
There. Tokyo to Turkish supermarket.
Türkiye is particularly vulnerable because it needs a great deal of foreign money.
The IMF estimates roughly $286 billion in outside financing is required this year, much of it to replace debts coming due.
Foreign investors aren’t supplying it because they developed a sentimental attachment to the Bosphorus. They want returns.
If Japan gives them a decent alternative, Türkiye may have to pay more to keep their attention.
The mortgage stays painful, the car loan ridiculous, and the manufacturer considering a new factory discovers that perhaps next year is a lovely time to reconsider.
No crash is required. That is the important—and magnificently boring—part. There need be no screaming traders, emergency television graphics or grim-faced officials marching toward microphones.
Tokyo merely has to become slightly less lousy a place to keep money.
That is the exquisite cruelty of global finance. A Japanese fund manager sits beneath fluorescent lights, drinks mediocre coffee, and decides that 3% at home beats an exotic adventure in Turkish debt.
He taps a keyboard. Nobody screams. No alarms sound. But five thousand miles away, the lira catches a chill.
Then the importer gets an invoice. The shopkeeper gets another.
Eventually a man in Istanbul sits down to breakfast, looks suspiciously at the bill and wonders how eggs, cheese and tea became participants in international monetary policy.
They didn’t, of course. Nobody invited international finance to breakfast.
But that is the small-print genius of the global economy: a bond yield twitches in Tokyo, money changes its mind, and eventually somebody in Istanbul gets a more expensive plate of eggs.
The Japanese bond market has never tasted menemen. It just found a way onto the bill.
It was all there in the terms and conditions.


 Set as preferred source
 Set as preferred source

 5 min read